

Crypto Tax Reporting: What Happens If You Don’t Report?

Failing to report your cryptocurrency transactions can lead to severe penalties, including fines of up to 75% of unpaid taxes, interest charges, and even prison time of up to 5 years. Starting in 2025, crypto exchanges will file detailed 1099 forms, making it easier for the IRS to detect unreported income. Here’s what you need to know:
- Crypto Is Taxable Property: Activities like trading, mining, staking, and receiving crypto as payment trigger tax obligations.
- IRS Enforcement Is Increasing: Advanced blockchain analytics and programs like “Operation Hidden Treasure” help the IRS track unreported transactions.
- Consequences of Non-Compliance:
- Financial: Penalties of up to 75% of unpaid taxes and fines up to $250,000.
- Legal: Criminal charges and potential imprisonment for tax evasion.
To stay compliant, maintain accurate records, use crypto accounting tools like Cryptoworth, and report all transactions correctly. Ignoring these rules is risky and costly.
Avoid costly penalties by using crypto tax and accounting software built for IRS reporting and digital asset compliance. A real-time crypto bookkeeping and reconciliation platform for 1099 form accuracy and audit readiness helps you stay compliant, organized, and protected as enforcement ramps up.
What Happens If You Don’t Report Crypto on Your Taxes?
What Happens If You Don’t Report Crypto Taxes?
Not reporting your cryptocurrency transactions can lead to serious trouble with tax authorities.
Fines and Interest for Not Reporting
The financial consequences of skipping crypto tax reporting can be steep. The IRS can slap you with penalties of up to 75% of the unpaid tax, plus interest on both the unpaid taxes and the penalties themselves [1]. For example, if you fail to report $10,000 in crypto income, you could face a penalty of $7,500, along with growing interest charges over time.
From 2025 onward, crypto exchanges will be required to file detailed 1099DA forms for capital gains and losses. This will make it much easier for the IRS to spot unreported transactions.
Legal Risks of Ignoring Crypto Tax Rules
The financial penalties are just the beginning – legal risks can be even more severe. Not reporting your crypto income can lead to fines of up to $250,000, penalties of 75% on unpaid taxes, and mounting interest charges. In extreme cases, you could even face up to 5 years in prison and criminal charges [1][6].
Take the case of Frank Richard Ahlgren III. He was charged for failing to report $4 million in bitcoin sales, showing the IRS’s ability to track large transactions.
The IRS uses advanced blockchain analytics to uncover unreported transactions. By working with companies like Chainalysis, they analyze public ledger data to identify suspicious activity and hidden income [4]. These tools make it increasingly difficult to hide crypto transactions.
With the IRS ramping up its monitoring efforts, it’s crucial to understand how it tracks cryptocurrency activity to avoid non-compliance.

Will MicroStrategy Have to REALLY Pay Billions of Bitcoin Taxes?

Bottom line: No, Microstrategy is not expected to owe billions of dollars in taxes with its unrealized gains in Bitcoin….

Two Lessons from the First Crypto Tax Evasion Case
Allgreen is the first Bitcoin investor to be sentenced to two years in prison, after he underreported the capital gains…
How Tax Authorities Track Crypto Transactions
Tracking Crypto with Blockchain Analytics
Tax authorities are stepping up their game with blockchain analytics to uncover unreported crypto income. For instance, the IRS works closely with firms like Chainalysis to trace transactions across various blockchains and exchanges. These tools help link anonymous wallets to real individuals, making it harder for crypto users to evade taxes.
IRS Actions That Show Their Tracking Power

The IRS has already made waves with its enforcement efforts. A notable case involves Frank Richard Ahlgren III, who was charged for not reporting $4 million in bitcoin sales. This case highlights how effective the IRS has become in identifying tax evasion through crypto [2].
The IRS has also introduced “Operation Hidden Treasure”, a program that combines criminal and civil investigations to uncover unreported digital assets. This initiative shows how serious the IRS is about cracking down on crypto tax violations.
On the global stage, tax authorities are teaming up to strengthen their enforcement capabilities. Some of the key methods they use include:
- Blockchain analytics to track transactions.
- Exchange reporting to gather user data.
- Operation Hidden Treasure for specialized investigations.
- Criminal investigations targeting severe cases.
Knowing how these methods work can help you stay on the right side of the law. Up next, we’ll dive into tools and strategies for accurate crypto tax reporting.
The Role of 1099-DA in IRS Crypto Enforcement
Failing to report crypto transactions has always been a risk, but with Form 1099-DA becoming mandatory in 2025, enforcement is expected to intensify. Previously, many crypto investors operated without receiving 1099 forms, making it easier to overlook reporting. Now, digital asset brokers must provide 1099-DA forms directly to both the IRS and taxpayers, ensuring that all crypto sales and trades are on record. This increased visibility means that failing to report digital asset transactions can lead to IRS audits, penalties, and potential tax liabilities.
How to Stay Compliant with Crypto Tax Rules
Using Cryptoworth for Crypto Tax Reporting
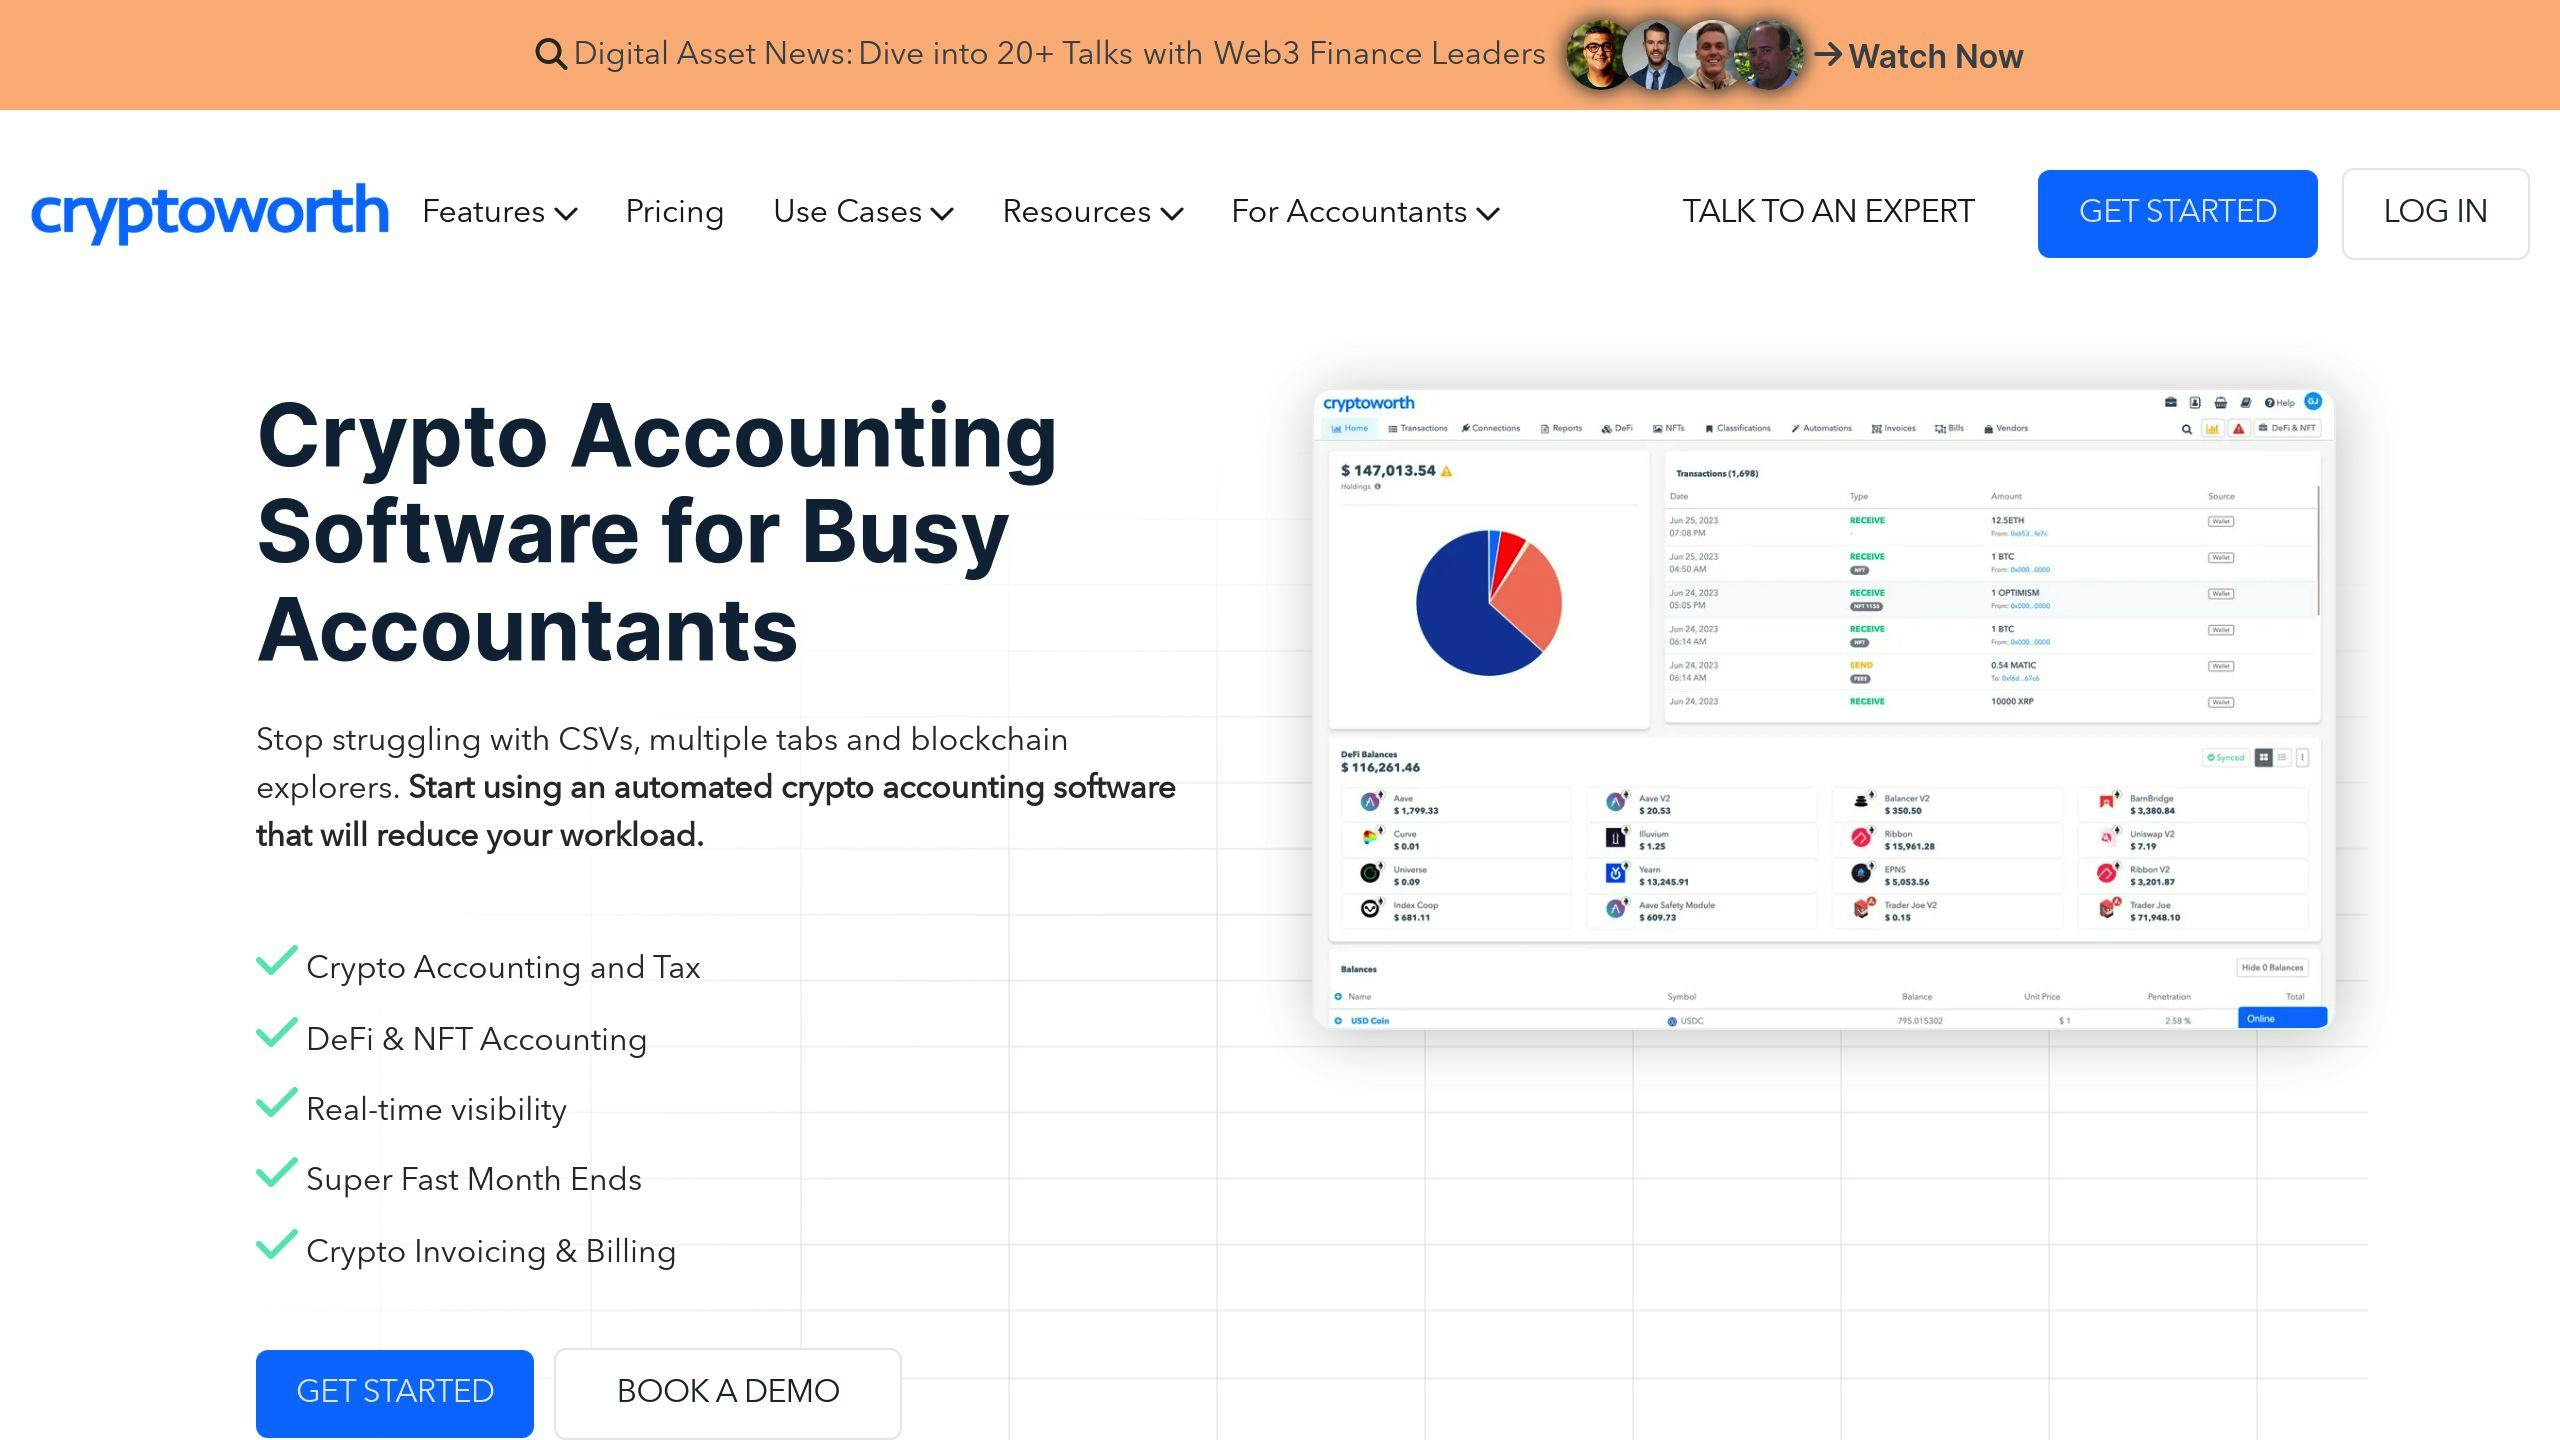
Cryptoworth makes crypto accounting and financial reporting easier by connecting to over 1,000 data sources and supporting more than 200 blockchains. Its automated tools handle classification and provide real-time insights, cutting down on mistakes and aligning with standards like US GAAP and IFRS. The platform also reconciles data from exchanges and wallets automatically, eliminating manual errors and supporting different accounting methods for both individuals and businesses.
With the IRS using advanced tracking tools, having a platform like Cryptoworth ensures your records are thorough and meet compliance requirements. While these tools help streamline the process, avoiding common pitfalls is just as important.
Common Crypto Tax Mistakes to Avoid
The IRS Criminal Investigation Division reported 390 crypto-related investigations between 2018 and 2023 [4]. Here are two critical errors to steer clear of:
- Not reporting all transactions: Blockchain analytics have become so advanced that hiding transactions is nearly impossible.
- Misclassifying transaction types: For instance, treating mining income as capital gains instead of ordinary income can lead to miscalculations and penalties.
Tips for Accurate Crypto Tax Reporting
The IRS is cracking down on unreported crypto assets, so accurate records are key to avoiding penalties. Here’s how to stay on top of your tax reporting:
- Keep detailed records of transaction dates, amounts, fees, and purposes with the help of automated tools.
- Track your portfolio daily to calculate cost basis accurately.
- Reconcile your accounts monthly instead of waiting until tax season.
- Use automated tools to monitor transactions across multiple platforms and blockchains.
Penalties for errors can be as high as 75% of the tax owed [3]. By maintaining thorough records and using reliable tools, you can minimize mistakes and stay compliant with tax regulations. Regular monitoring and proper practices are your best defense against costly errors.
Conclusion: Why Reporting Crypto Taxes Is Worth It
Key Takeaways
Cryptocurrency tax enforcement has come a long way. Between 2018 and 2023, the IRS Criminal Investigation Division investigated 390 crypto-related cases [4]. With initiatives like “Operation Hidden Treasure” and advanced blockchain analytics, the IRS has shown it’s serious about uncovering unreported digital assets. Add to that global cooperation and cutting-edge technology, and hiding transactions has become nearly impossible.
Given these risks, staying compliant isn’t just about following the law - it’s also a smart financial move.
Prioritizing Compliance
The IRS’s increasing focus on blockchain analytics and enforcement programs underscores the dangers of ignoring tax obligations. With tools like Cryptoworth, businesses can simplify compliance while avoiding hefty penalties and interest charges.
Cryptoworth supports over 1,000 data sources and 200+ blockchains, making it a robust solution for managing complex crypto portfolios. The platform ensures accurate record-keeping and streamlined reporting, which are critical for complying with Rev. Proc. 2024-28.
Reporting crypto taxes doesn’t take much effort when compared to the potential penalties for non-compliance. By keeping accurate records and using dependable software, you’re safeguarding your financial future. Modern automated tools make compliance easier than ever, leaving no excuse to avoid meeting tax responsibilities.
Modern automated tools like Cryptoworth remove much of the burden associated with crypto tax reporting, leaving no excuse to delay meeting these new responsibilities.
Watch these highlights from the Rev. Proc. 2024-28 workshop to learn more about its Safe Harbor and how it can help:
FAQs
What happens if I don’t report crypto on taxes?
Failing to report crypto transactions can result in audits, hefty fines, or even criminal charges. The IRS may impose penalties of up to $100,000 for individuals [1]. Recent examples highlight stepped-up enforcement, including targeted investigations and prosecutions for tax evasion.
Can you go to jail for not paying crypto taxes?
Yes, evading crypto taxes can lead to jail time. The maximum penalty includes up to five years in federal prison [1]. Between 2018 and 2023, the IRS Criminal Investigation Division handled 390 crypto-related cases, with 224 leading to prosecution recommendations [4].
What is the tax penalty for crypto?
Penalties for crypto tax evasion can include fines of up to $100,000 for individuals, $500,000 for corporations, and imprisonment for up to five years [1]. The IRS uses advanced tracking techniques and international collaborations to enforce these rules.
Tools like Cryptoworth can simplify crypto tax reporting by accurately tracking transactions and ensuring compliance with tax laws. Keeping detailed records and monitoring your activity regularly are crucial steps to avoid costly penalties.

Leave a Comment